Regulation
Disclosure by design — when data rooms meet ledgers
Tokenisation makes disclosure more useful only when the evidence behind an asset remains intelligible, governed and open to challenge.
Thursday, 15 October 2026 · 09:00 UTC (demo) · 4 min read · 998 words
 Democratize
The document is not the disclosure
A data room can be full and still leave an investor poorly informed. Documents accumulate, versions multiply and the explanation of what matters often sits in correspondence rather than the formal record. Tokenisation does not remove this problem. It can make the relationship between an investment and its supporting information more explicit, but only if someone first decides what that relationship should be. The starting question is not which files belong on a ledger. It is which claims an investor needs to test, and what evidence would allow that testing to happen.
For a real asset, those claims cross several boundaries. Ownership may depend on one set of records, valuation on another, and distributable income on contracts that change over time. Planning conditions, insurance exclusions and financing covenants can alter the meaning of an apparently straightforward asset description. A digital representation of an interest should therefore point towards a coherent account of rights and dependencies, rather than simply a larger collection of attachments. Disclosure becomes useful when the reader can distinguish a material limitation from background documentation without relying on the issuer's preferred narrative.
Design the evidence trail
Disclosure by design begins before subscription documents are finalised. Each important statement should have an identifiable source, an accountable owner and a review process. If an offering describes rental income, for example, the supporting evidence needs to distinguish contracted rent from collected cash, and both from forecasts. A ledger might record when an approved disclosure package was published or establish that a document has not changed. It cannot establish that the original statement was complete, that the assumptions were reasonable or that the source was independent.
This distinction matters because technical integrity and substantive reliability answer different questions. A cryptographic reference can help detect a substituted file. It does not validate a surveyor's judgement or resolve an ambiguity in a lease. Investors still need access to qualifications, methodologies and conflicts. Where material evidence remains off-chain, the arrangements for preserving and retrieving it become part of the investment infrastructure. Broken links, expired permissions and departed service providers are not merely administrative inconveniences when they interrupt the ability to understand an enforceable right.
The design should also accommodate disagreement. A valuation may be contested without being fraudulent; an estimate may change without making the previous disclosure improper. A useful record preserves what was known, what was assumed and why a revision occurred. Overwriting yesterday's account with today's cleaner presentation defeats much of the purpose. The aim is a traceable sequence of judgements, not a permanent suggestion that uncertainty has been eliminated. Investors should be able to reconstruct the decision environment rather than encounter only its latest summary.
Access is a governed right
Not every participant should see every document. Commercial confidentiality, personal information and contractual restrictions can make unrestricted publication inappropriate. Professional investors may also need different levels of access at different stages of diligence. The relevant design problem is therefore controlled availability, not indiscriminate transparency. Who can grant access, who can revoke it, and what happens after a transfer should be settled alongside the security's economic terms. A prospective purchaser needs enough information to assess the interest without inheriting permissions that expose unrelated confidential material.
A reliable ledger can preserve a disclosure trail; it cannot substitute for the judgement that makes disclosure meaningful.
Corrections require equally careful treatment. A persistent record should not become an excuse to circulate inaccurate personal information indefinitely. Legal advice is needed on retention, rectification and the relationship between an immutable reference and a changeable underlying document. In practice, some information may belong in governed repositories rather than directly on a shared ledger. That is not a retreat from tokenisation. It is recognition that durable evidence and responsible information management must be designed together, with clear responsibilities when those objectives appear to conflict.
For family offices and GCC institutions assessing UK assets, this access model also has a practical dimension. Investment teams, external counsel and advisers may work across jurisdictions and internal approval chains. A coherent disclosure process should make authorised review reproducible without assuming that every participant uses the same platform. Exportable records, clear document hierarchies and understandable permissions may matter more than a polished interface. Cross-border accessibility does not remove local legal requirements, nor does a common technical format create a common interpretation of the rights being offered.
Disclosure after the subscription
The strongest test comes after capital has been committed. Investors need to know which developments trigger an update, who determines materiality and how information reaches holders when ownership changes. A covenant breach, delayed payment or revised asset plan should not disappear between an administrator's workflow and an investor portal. Automated alerts can support the process, but judgement remains necessary. Someone must decide what the event means, which obligations it engages and whether the existing disclosure still gives a fair account of the investment.
That continuing responsibility should be visible in the economics and governance of the arrangement. Reporting costs, service-provider replacement and access during distress deserve attention before the investment is issued. If the sponsor fails or a platform closes, the investor should not lose the evidence needed to establish a claim. Institutional diligence can reasonably ask for continuity plans and practical demonstrations of record retrieval. A disclosure architecture that works only while every party cooperates is least dependable at the moment when dependable information becomes most valuable.
For Democratize, as a pre-launch UK arranger, this is a useful organising principle rather than a claim about an operating service: connect the proposed digital instrument to an intelligible chain of evidence, responsibility and recourse. Regulatory analysis still depends on the rights, activities and jurisdictions involved; a token label settles none of those questions. The more credible direction for the market is not disclosure without friction, but disclosure whose necessary frictions are visible and managed. Better records should make difficult questions easier to ask, not encourage investors to stop asking them.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
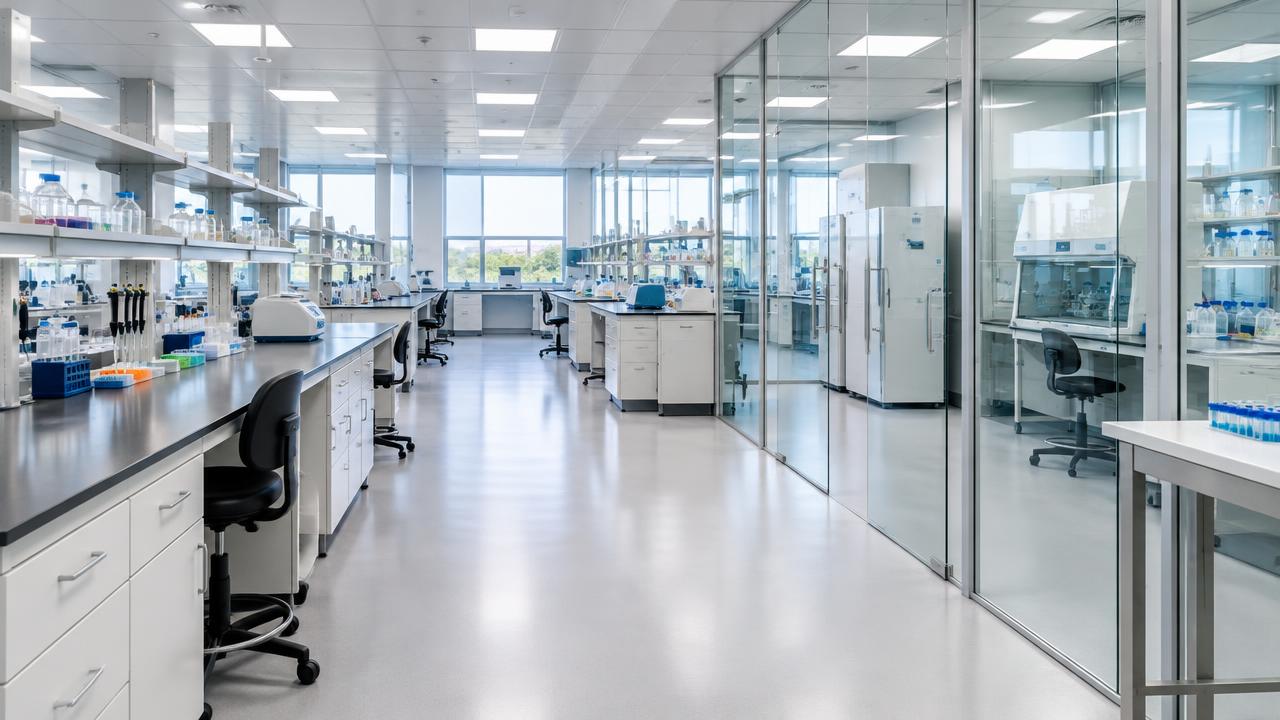 Mezzanine note: Oxford lab spaceBig ticket · £18m illustrative asset valueTokenised fund units
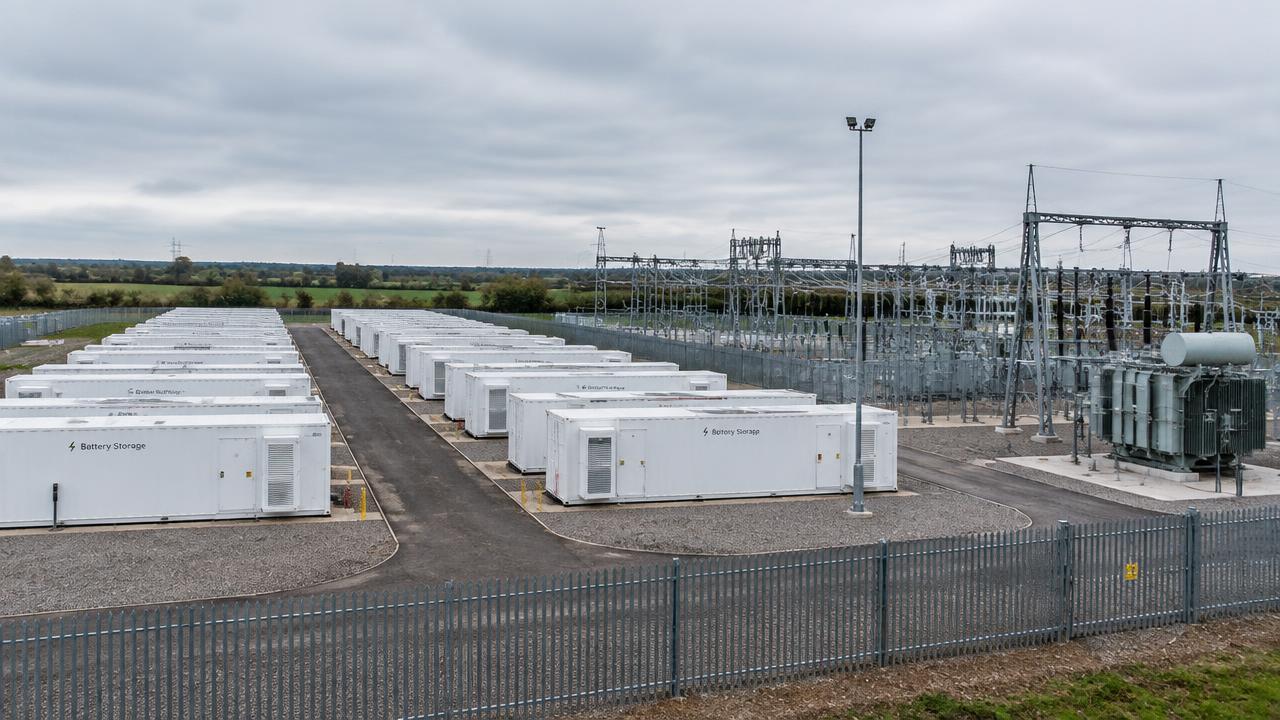 DLT bond: fictional community energy projectLow ticket · £750k illustrative asset valueDemonstration permissioned DLT bond register
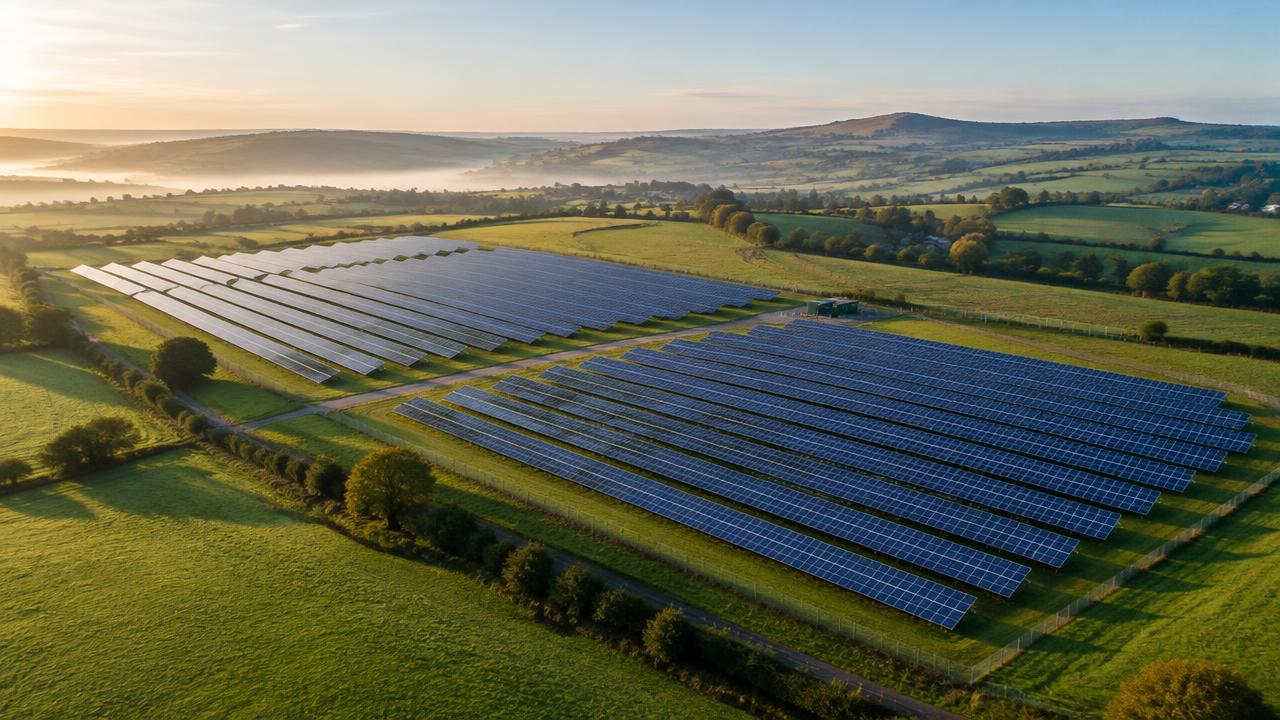 DLT bond: fictional energy pilotEntry-level scale · £75k illustrative asset valueDemonstration permissioned DLT bond register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.