Investors
Gulf capital and the London–Gulf tokenisation corridor
A credible London–Gulf corridor would rest on aligned mandates, enforceable structures and reliable servicing rather than a shared enthusiasm for digital assets.
Monday, 5 October 2026 · 09:00 UTC (demo) · 4 min read · 959 words
 Democratize
A corridor is a relationship
The idea of a London–Gulf tokenisation corridor is attractive because it connects two conversations that are often conducted separately. One concerns the financing of real assets through established legal and professional structures. The other concerns new ways to record, distribute and administer investment interests. Bringing them together could make cross-border participation more legible. It would not, by itself, create investor demand or remove the obligations that accompany a financial promotion, a securities offering or a transfer of ownership.
London can be considered a structuring and advisory centre without assuming that every transaction should be governed there. The Gulf, meanwhile, is not a single pool of capital with a uniform appetite. Sovereign institutions, family offices, banks and specialist investment firms can have markedly different objectives. Some may prioritise income visibility; others may seek strategic exposure, control or diversification. Geography provides context, but the investment mandate remains the more useful starting point.
A functioning corridor would therefore be a repeatable framework for trust rather than a route along which tokens simply travel. It would connect underwriting standards, professional responsibilities and investor reporting. The measure of progress would be whether each participant understands the asset, the rights being acquired and the practical consequences of holding them across jurisdictions.
Start with the mandate
A discussion about tokenised exposure should begin with ordinary investment questions. What generates cash? Which risks can interrupt it? How much discretion does the manager retain? What information will the investor receive, and what decisions can the investor influence? These questions matter whether the asset is a leased building, a logistics facility or a private lending arrangement. A digital instrument cannot compensate for an unclear investment thesis or a structure that conflicts with the buyer’s mandate.
Family offices should not be treated as interchangeable with institutional funds. Their governance arrangements, decision processes and liquidity needs may differ substantially, including within the same family group. An investment committee might welcome more consistent reporting while remaining indifferent to the underlying ledger. Another allocator might be interested in digital administration but unwilling to accept unfamiliar custody or recovery arrangements. Neither position is inherently contradictory.
Where Sharia considerations are relevant, they require substantive attention to the structure, assets and contractual relationships. Tokenisation does not establish compliance, and a label cannot substitute for appropriate review. Nor should every Gulf investor be presumed to require the same framework. Early clarity about mandate constraints prevents technology discussions from obscuring the questions that will ultimately determine whether a proposal can proceed.
Regulation does not travel automatically
The London–Gulf shorthand can conceal important jurisdictional distinctions. The FCA, DFSA, VARA and the regulatory framework within ADGM are relevant reference points in different contexts, not interchangeable authorities. Their relevance depends on the activity, instrument, entity and location involved. A permission associated with one business or jurisdiction should never be treated as a general passport for arranging, marketing, custody or trading elsewhere.
Cross-border distribution also involves more than the issuer’s location. The place where an investor is approached, the status of that investor and the role of each intermediary may all matter. Restrictions need to be mapped before materials circulate, not rationalised afterwards. Professional investor status can change the applicable framework, but it is not a universal exemption from obligations or an assurance that a product is suitable for a particular institution.
A credible capital corridor carries clear responsibilities in both directions, not just investment propositions in one.
Legal analysis should distinguish the underlying asset from the instrument through which exposure is offered. A UK property interest held through a vehicle raises different questions from a direct lending claim or an interest in a fund. Tax treatment, enforcement, insolvency and dispute resolution can all affect the economic result. A common digital interface may make these structures look similar while leaving their consequences materially different.
Service the relationship after settlement
The less glamorous work begins after an allocation. Investors need coherent statements, timely explanations of covenant developments and a clear account of distributions. Where assets and investors operate in different currencies, reporting should distinguish underlying performance from currency effects. Where different working calendars or approval chains affect administration, those dependencies should be reflected in realistic processes rather than discovered when an urgent consent is required.
Governance must also survive a difficult period. Who communicates when a borrower misses a payment? Which party can negotiate amendments? How are conflicts handled if different investor groups favour different outcomes? Tokenised voting or automated notices may assist administration, but the authority to act must come from the governing documents. An efficient message does not make an ambiguous consent valid, and a recorded vote does not necessarily resolve a conflict of interest.
A credible operating model should accommodate investor preferences without creating an unmanageable collection of exceptions. This could mean consistent core reporting alongside appropriate language support, clearly defined information rights and agreed channels for material decisions. The objective is institutional reliability, not personalisation at any cost. Excessive bespoke arrangements can weaken comparability and place too much knowledge with individual relationship managers.
For Democratize, a pre-launch UK arranger, the corridor is best understood as a design challenge rather than an existing achievement. The opportunity worth examining is whether disciplined structuring and digital administration could make suitable real-asset propositions easier for professional audiences to assess. That requires patient work on mandates, documentation and servicing before any claim about distribution efficiency becomes meaningful.
The eventual test is straightforward: would the relationship remain workable if the tokenisation terminology disappeared from the presentation? If the answer depends on sound assets, clear rights and accountable counterparties, technology may strengthen it. If the answer depends mainly on novelty, the corridor is still a marketing idea rather than a durable financial relationship.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
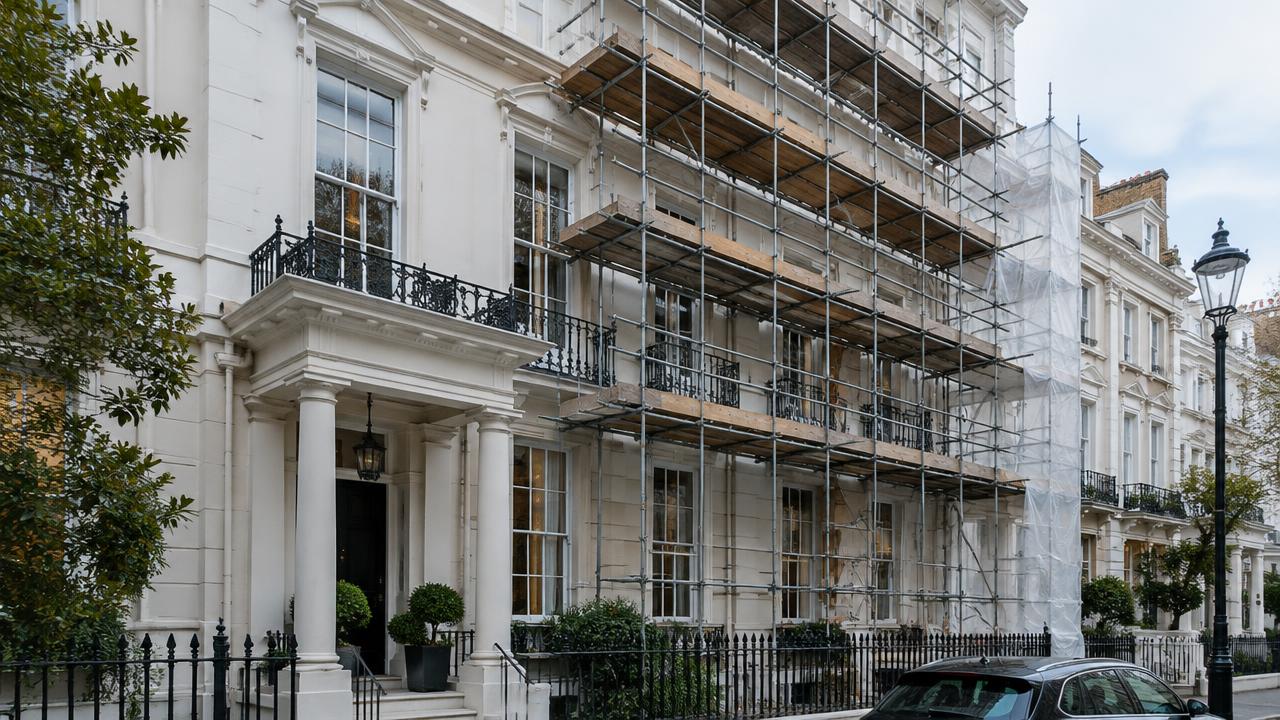 Bridging loan: Mayfair townhouse refurbishmentMedium ticket · £9.0m illustrative asset valueERC-3643 on a permissioned EVM chain
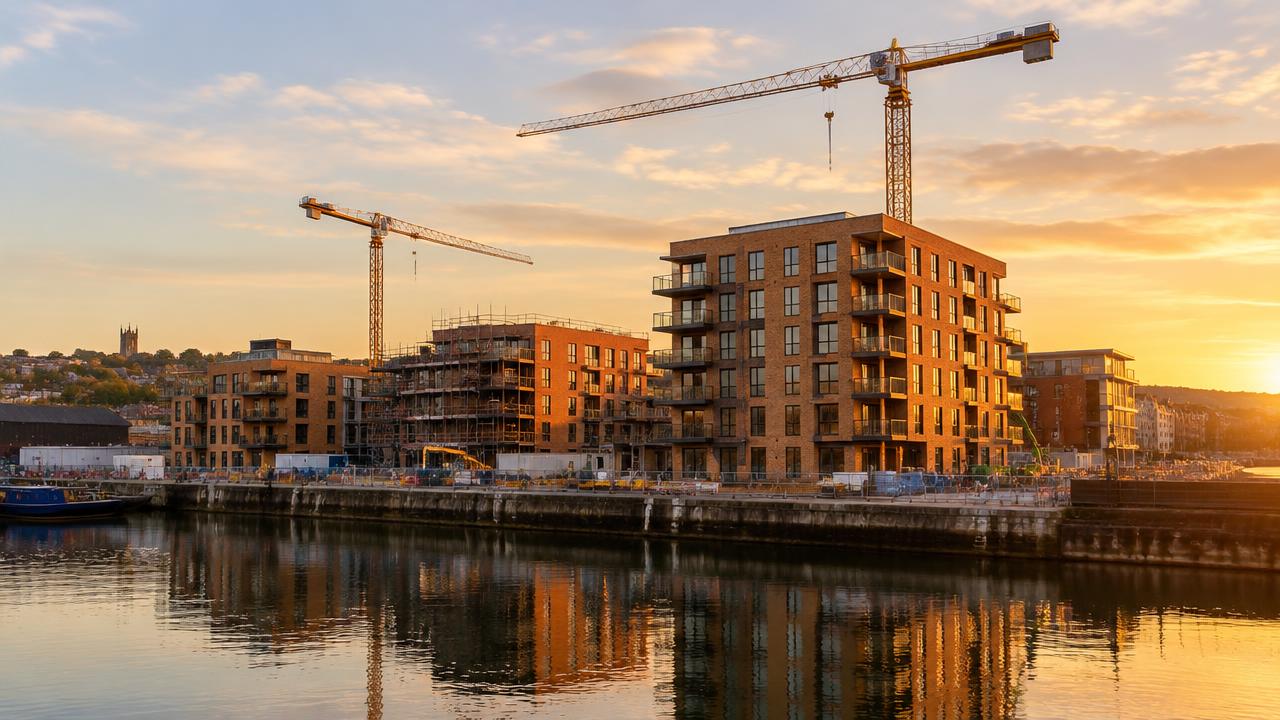 Development loan: Bristol residential schemeBig ticket · £26m illustrative asset valueERC-3643 on a permissioned EVM chain
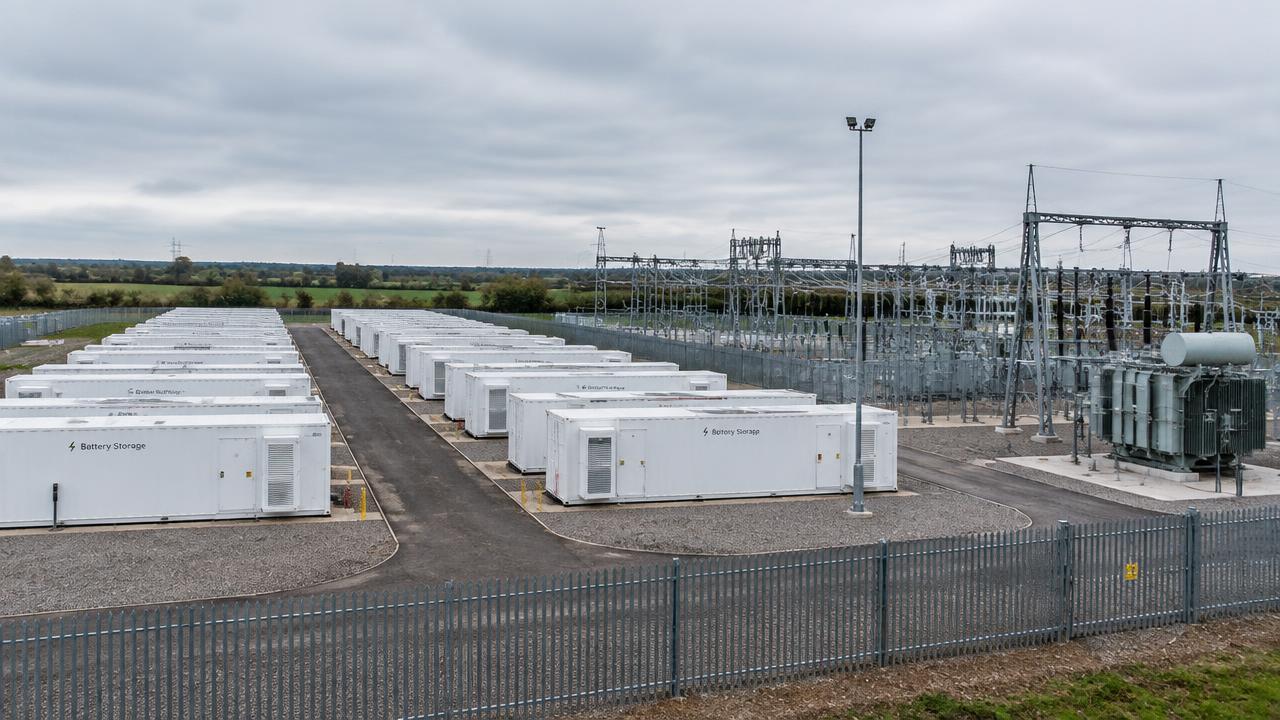 DLT bond: fictional community energy projectLow ticket · £750k illustrative asset valueDemonstration permissioned DLT bond register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.