Investors
What institutional due diligence of a tokenised deal looks like
Institutional scrutiny starts with enforceable rights and follows every dependency between the underlying asset, the digital record and the investor's ability to recover value.
Thursday, 22 October 2026 · 09:00 UTC (demo) · 4 min read · 1,010 words
 Democratize
Begin without the token
A useful first exercise in institutional diligence is to remove the token from the presentation. What remains: a loan, a share, a beneficial interest, a contractual participation or something else? Who owes the investor a duty, and where can that duty be enforced? The answers establish the investment's legal and economic substance. Only then does it become useful to ask what a ledger adds. Starting with the interface risks allowing the method of administration to stand in for an explanation of the underlying rights.
The asset itself still requires ordinary scrutiny. For property, this could include title, leases, physical condition, financing and the assumptions behind a valuation. For infrastructure, it may involve concessions, counterparties, maintenance obligations and demand exposure. The work follows the actual proposal rather than a universal tokenisation checklist. Institutional teams also distinguish independently verified evidence from sponsor representations. A document may be authentic and still incomplete, while a persuasive investment narrative may depend on assumptions that belong in a sensitivity analysis rather than the statement of established facts.
Map rights across every layer
The next task is to draw the chain linking the investor to the asset. Issuing vehicles, nominees, trustees, custodians and administrators may each play a role. Every additional layer creates questions about authority, liability and continuity. Investors need to understand whether the digital record establishes legal ownership, evidences a separate register or merely instructs another system. When records disagree, which prevails? A technically successful transfer may have different legal consequences depending on the documents and applicable law. That hierarchy should be explicit before any subscription is considered.
Cash deserves its own map. Where does operating income arrive, who controls the account and which deductions precede distributions? Segregation, reconciliation and payment authorisation need more than reassuring descriptions. An institution may seek evidence of the controls and examine how they function when a person is absent or a provider fails. If settlement uses a digital payment instrument, that introduces another exposure to assess. The asset's credit risk and the risks of the payment mechanism should remain distinguishable rather than disappearing into a single claim of seamless settlement.
Regulatory diligence runs alongside this analysis, not after it. The relevant questions concern the instrument, the activities performed, the parties involved and the jurisdictions in which it is offered or held. References to the FCA, MiCA or the EU DLT Pilot Regime are not substitutes for a reasoned perimeter assessment. Different frameworks address different subjects. Institutional reviewers need to know which permissions or exemptions are relied upon where relevant, what limitations attach to them, and who is accountable for keeping that analysis current as the arrangement changes.
Test the operating model
Technology review should connect technical controls to investment consequences. Who can issue, freeze, transfer or cancel an interest? How are privileged permissions held and changed? What happens if a key is lost, compromised or used without authority? A security review of software is useful evidence, but it is not a guarantee of safe operation. Deployment choices, access controls and human procedures can alter the practical risk. Investors should understand the difference between code that has been reviewed and an entire service that has been tested under realistic conditions.
Due diligence is complete only when the rights described in the documents can survive the failure of the systems that administer them.
Custody raises questions that cannot be answered by naming a wallet. An institution needs to know who controls the relevant credentials, what recovery mechanisms exist and how assets are treated if a provider becomes insolvent. Some investors may prefer an intermediary arrangement; others may have different operational requirements. Neither preference removes the need for legal analysis and tested procedures. The arrangement should also explain how a court order, an erroneous transfer or a disputed instruction is handled without pretending that technical finality automatically resolves every legal question.
Reporting and valuation require an operating discipline of their own. Which information is delivered, how often is it reviewed, and who challenges a stale assumption? A ledger can record events without explaining their economic significance. Institutions need reports that connect changes in the asset to cash flow, covenant compliance and valuation judgements. They also need a way to retain records outside a single provider's interface. Reproducible data and clear reconciliations matter because internal risk, finance and compliance teams may examine the same investment for different purposes.
Rehearse the uncomfortable scenarios
A serious diligence process asks participants to walk through failure rather than merely describe normal operations. Suppose the sponsor becomes insolvent, distributions stop and the technology provider ceases supporting the platform. Who holds the authoritative ownership record? Who can appoint replacements? Which costs must be paid before investors receive anything? Answers should be supported by documents and workable procedures. A business continuity policy has limited value if it assumes cooperation from the very party whose failure has triggered the problem. Dependency analysis should identify those circular arrangements early.
Liquidity should receive the same sceptical treatment. Permission to transfer is not evidence of demand, and a displayed price may not represent an executable transaction. Institutions will consider eligibility restrictions, settlement arrangements, information access for purchasers and the possibility of holding through maturity or enforcement. They may also examine concentration limits and how the exposure fits internal mandates. For a family office or GCC institution, operational convenience does not override portfolio governance. A tokenised structure must be assessable within those existing disciplines, not presented as an exception to them.
For Democratize, as a pre-launch UK arranger, the implication is straightforward: institutional readiness should be treated as a standard of evidence, not a marketing designation. Clear rights, documented dependencies and candid treatment of uncertainty make a proposal easier to interrogate. They do not guarantee approval or remove commercial risk. The strongest case for tokenisation is that it may make some parts of ownership and administration more coherent. Institutional diligence asks whether that coherence persists beyond the demonstration, through an ordinary reporting cycle and into the difficult circumstances in which enforceability matters most.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
 Senior note: London logistics warehouseBig ticket · £48m illustrative asset valueTokenised SPV share register
 Bridging loan: Mayfair townhouse refurbishmentMedium ticket · £9.0m illustrative asset valueERC-3643 on a permissioned EVM chain
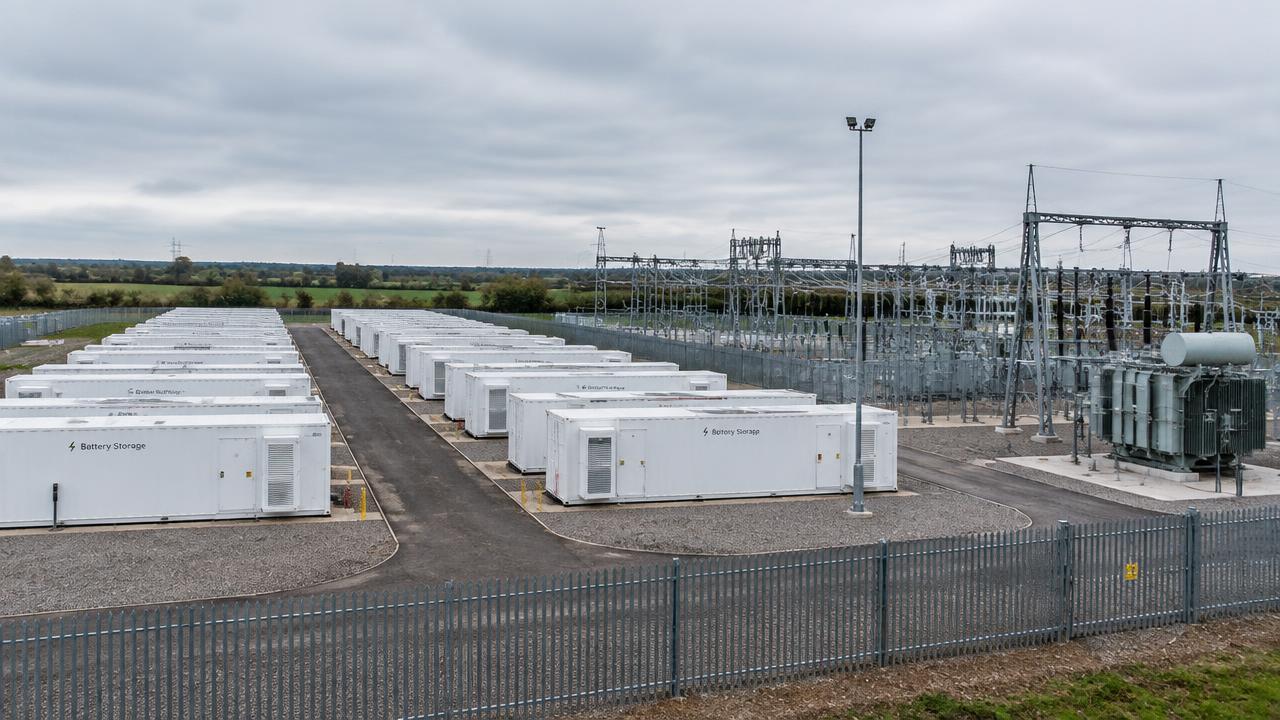 DLT bond: fictional community energy projectLow ticket · £750k illustrative asset valueDemonstration permissioned DLT bond register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.