Real estate
Real estate credit on-chain — what actually changes for lenders and borrowers
Digital loan records may improve administration, but property lending still turns on security, servicing and the borrower's capacity to repay.
Monday, 7 September 2026 · 09:00 UTC (demo) · 4 min read · 965 words
 Democratize
Start with the credit, not the token
Real estate credit begins with a familiar exchange: capital is advanced against a promise of repayment, supported by an agreed package of rights. The lender examines the property, the borrower, the business plan and the route to repayment. Representing an interest in that loan on a digital ledger does not alter this starting point. Rental income can disappoint, development can stall and refinancing can become difficult regardless of how ownership is recorded.
What tokenisation can change is the organisation around the loan. Investor interests might be recorded differently, payment information might move through a more connected process and transfers might require fewer manual steps. These are potentially useful changes, but they should be described precisely. An investor may hold a direct claim, an interest through a vehicle or a contractual participation. The token alone does not reveal which arrangement applies or who can enforce it.
The distinction is especially important when marketing language compresses several legal layers into the phrase property-backed. A claim against a vehicle is not necessarily a direct mortgage interest. Security may be held by a trustee or agent for a defined group of creditors. Priority, enforcement powers and the treatment of proceeds depend on the documentation. A digital record can make the structure easier to navigate, but cannot substitute for understanding it.
What lenders might gain
Loan administration often relies on information travelling between borrowers, servicers, agents and investors. Interest calculations, covenant certificates and consent requests may arrive through separate channels. A coordinated system could reduce repeated data entry and provide a clearer history of approvals. For a lender, the benefit would be less uncertainty about the status of an obligation, rather than a fundamentally different source of return. That benefit depends on reliable inputs and clearly assigned responsibilities.
A ledger can show that a report was submitted or an instruction approved. It cannot establish that a valuation is sound or that a construction milestone was properly achieved. Those judgements still require evidence and, where appropriate, independent expertise. The same applies to financial covenants: automating a calculation is useful only when the definitions, source data and exceptions are understood. An incorrect input can become more consequential when it triggers an action automatically.
Lenders also need a coherent approach to amendments. Property finance rarely follows an entirely frictionless path from drawdown to repayment. Extensions, partial releases, revised budgets and waivers may be commercially sensible. The operating model must identify which decisions require investor consent, how voting rights are determined and how changes reach the authoritative records. An immutable history can support accountability; it should not be confused with an inability to amend a contract lawfully.
Putting a loan on-chain changes its administration before it changes its credit risk.
What borrowers should examine
For borrowers, the attraction may be a more orderly interface with capital providers. Clearer reporting requests and fewer inconsistent instructions would have practical value. But a digital structure could also add work if the borrower must maintain existing reporting while feeding another platform. The relevant comparison is the full burden of compliance, including data preparation, approval processes and the cost of correcting mistakes, not simply the convenience of an initial transaction.
Borrowers should also understand who sits across the table when circumstances change. A dispersed investor base may rely on a security agent or representative, but the authority of that representative needs to be clear. Transferability can alter the identity or composition of the creditor group. Confidential information about tenants, leases or a development budget should not become broadly accessible merely because ownership records are shared. Permissioning and confidentiality are central commercial terms.
Neither faster settlement nor a more accessible interface guarantees a lower financing cost. Pricing reflects expected losses, capital availability, duration, security and the negotiating position of the parties. Technology may remove particular administrative costs, while introducing expenses for custody, integration or specialist oversight. Whether any saving reaches the borrower depends on the structure and competition. A credible proposal separates operational efficiency from claims about cheaper capital, rather than assuming one necessarily produces the other.
Default is the decisive test
The most revealing questions arise when the loan stops performing. Who serves notices? Who determines whether an event of default has occurred? Who can instruct enforcement, and how are competing interests handled? Property rights and insolvency processes remain anchored in applicable law. A digital transfer cannot make those processes instantaneous or remove disputes over valuation, priority and the appropriate timing of a sale.
Cash control matters just as much. Rental receipts, reserve accounts and enforcement proceeds may sit within conventional banking arrangements. Investors need to understand how those accounts relate to the digital record and who reconciles the two. If a platform or service provider fails, the structure should still support access to records, continued servicing and the exercise of legal rights. Business continuity is part of the credit architecture, not an optional technology feature.
Secondary transfers deserve similar realism. An eligible investor may be able to transfer an interest more efficiently, but a property loan remains a specific credit exposure. A potential buyer will examine current performance, documentation and the remaining term. Without that information, a technically transferable position may still be difficult to sell. Better records can reduce diligence friction; they cannot create demand for a risk that buyers do not want.
For institutional capital, the sensible benchmark is therefore a well-run conventional loan, not an idealised paper process designed to make every digital alternative appear superior. Tokenisation earns attention where it improves traceability, servicing discipline or coordination without weakening legal clarity. For borrowers and lenders alike, the durable question is whether the structure remains comprehensible through repayment, amendment and distress. The medium should support that understanding, never distract from it.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
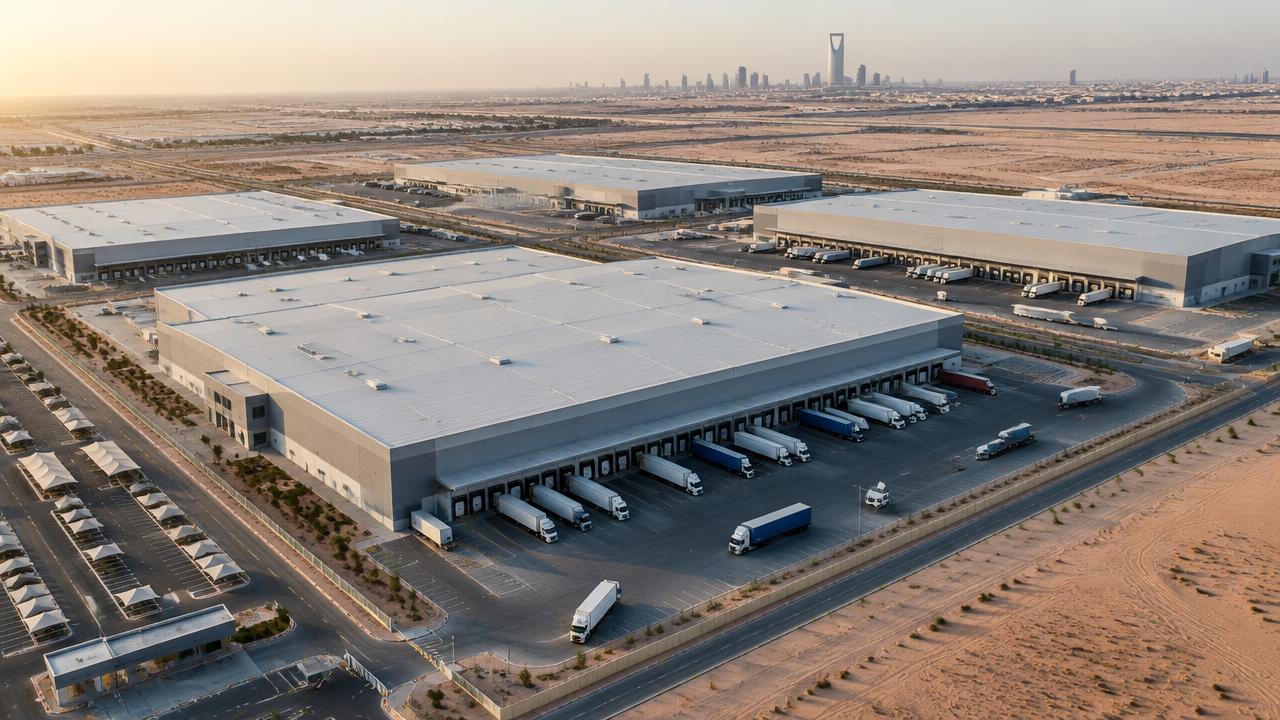 Senior note: Riyadh logistics parkBig ticket · £64m illustrative asset valueERC-3643 on a permissioned EVM chain
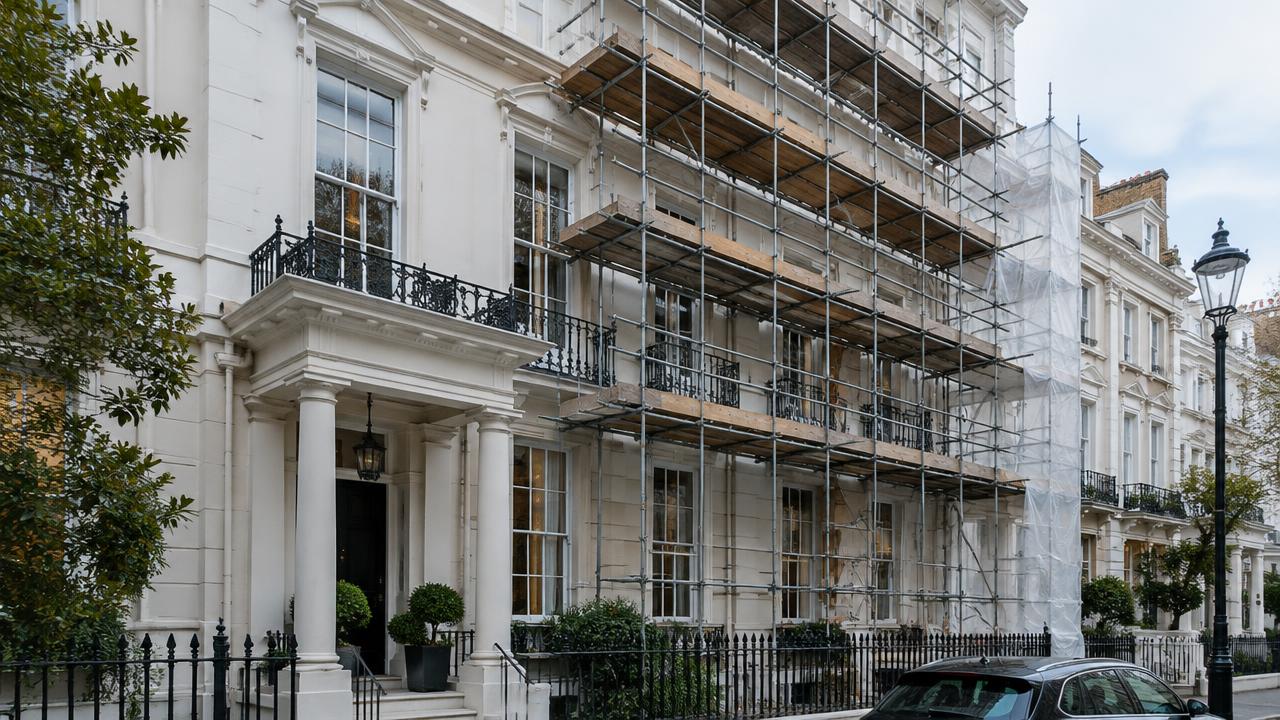 Bridging loan: Mayfair townhouse refurbishmentMedium ticket · £9.0m illustrative asset valueERC-3643 on a permissioned EVM chain
 Mezzanine note: Oxford lab spaceBig ticket · £18m illustrative asset valueTokenised fund units
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.