Markets
Why tokenisation is a plumbing story, not a product story
The meaningful test of tokenisation is whether it improves the machinery beneath an investment without obscuring the rights above it.
Thursday, 3 September 2026 · 09:00 UTC (demo) · 4 min read · 969 words
 Democratize
The asset is not the interface
Tokenisation is often introduced through the object an investor can see: a digital unit, a wallet balance or a transferable record. That is an understandable starting point, but a poor place to finish. A token does not explain what an investor owns, how income reaches them or what happens when a borrower defaults. Those answers sit in contracts, ownership structures, servicing arrangements and the legal system. The visible instrument is only the entrance to a much larger machine.
For professional investors, the relevant question is therefore not whether an asset can be represented on a ledger. It is whether that representation improves the way an investment is issued, held, administered and transferred. A property loan remains exposed to repayment risk. An infrastructure interest still depends on contractual cash flows and operational performance. Changing the record cannot remove the underlying economics, although it may change how effectively those economics are observed and managed.
This distinction matters because product language can conceal infrastructure costs. A simple subscription screen may depend on several intermediaries reconciling separate records behind it. Conversely, an apparently unremarkable instrument may have a genuinely better operating model. The useful comparison is not between an old certificate and a new token. It is between complete processes, including the awkward moments when instructions conflict, records disagree or someone needs to reverse an error.
Where the friction actually sits
Conventional investment administration contains repeated handovers. An investor submits information, an administrator checks eligibility, a bank receives money and another system updates the ownership register. Distributions, transfers and reporting create further exchanges. Each handover has a reason, often rooted in accountability or regulation. Yet the same information can be copied repeatedly, checked against inconsistent sources and reconciled after the event. Tokenisation becomes interesting where it reduces unnecessary duplication without removing necessary responsibility.
A shared record can make agreement easier, provided participants agree what that record means. An entry might represent legal title, a beneficial interest or merely an instruction awaiting approval. These are different propositions. If the authoritative register remains elsewhere, the token record needs a defined relationship with it. If the ledger itself carries legal significance, the arrangements must explain who can correct it and under which circumstances. Technical finality and legal finality should never be treated as synonyms.
The cash leg deserves equal attention. Recording a securities transfer quickly does not complete settlement if payment arrives through a disconnected process. Participants need to understand the settlement asset, the payment provider and the conditions under which both legs become binding. Delivery against payment is a design objective, not a phrase that resolves every dependency. Faster movement can reduce some exposures while making operational mistakes harder to interrupt.
Better plumbing is valuable only when the rights, responsibilities and cash flows remain intelligible.
Programmability needs a rulebook
Programmable instructions can support distribution calculations, transfer restrictions and routine reporting. Their appeal is consistency: an agreed rule can be applied without someone rekeying the same instruction. But a programme is not a substitute for judgement where the facts are disputed. Covenant waivers, sanctions questions, disputed valuations and insolvency proceedings do not become straightforward because an instrument has a digital representation. Automation must have a clearly bounded role within a wider governance framework.
The practical questions are familiar to anyone who has scrutinised a service agreement. Who approves changes? Who can pause an incorrect payment? What happens if a key is lost or a service provider becomes unavailable? How are investors notified of amendments? These are not objections to technological progress. They are the means by which an institutional operating model becomes credible. A process that works only while every participant behaves perfectly is not a robust process.
Privacy also complicates the ideal of a single shared record. Investors may want verifiable ownership and timely reporting without revealing their positions to every network participant. Borrowers may have legitimate confidentiality obligations. Access controls, data minimisation and the division between on-chain records and external documents therefore belong in the initial design. Adding them later can undermine the apparent simplicity that made the proposal attractive in the first place.
Liquidity remains an economic question
One of the least helpful shortcuts is to equate transferability with liquidity. A system may permit a transfer while no suitable buyer exists. A buyer may exist but require information that is not readily available. Restrictions may reflect investor eligibility, contractual consent or the nature of the asset itself. Smaller units can change access and administration, but they cannot guarantee a competitive market or a reliable exit price.
For real assets, this distinction is particularly important. Their cash flows are specific, their documentation can be bespoke and their valuation may require judgement. A more efficient transfer process can be useful without creating continuous trading. The honest proposition is narrower and stronger: reduce avoidable friction where a willing, eligible counterparty is already present. Claims beyond that require evidence about demand, market structure and the economics of maintaining a venue.
An institutional assessment should consequently examine the whole lifecycle. That includes onboarding, issuance, custody, income processing, secondary transfers, default management and eventual redemption. Costs should include integration, oversight, cybersecurity and the possibility of moving away from a provider. A cheaper issuance process is not necessarily a cheaper investment structure if servicing becomes more complex or resilience depends on a single supplier.
For Democratize, as a pre-launch UK arranger, the editorial starting point is that connecting real assets with institutional capital requires clarity before novelty. Professional investors, family offices and GCC capital do not form one homogeneous audience, but each needs an understandable account of ownership, risk and recourse. Tokenisation may improve that account's operational delivery. Its strongest case is not a new label for the asset, but a more dependable system around it.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
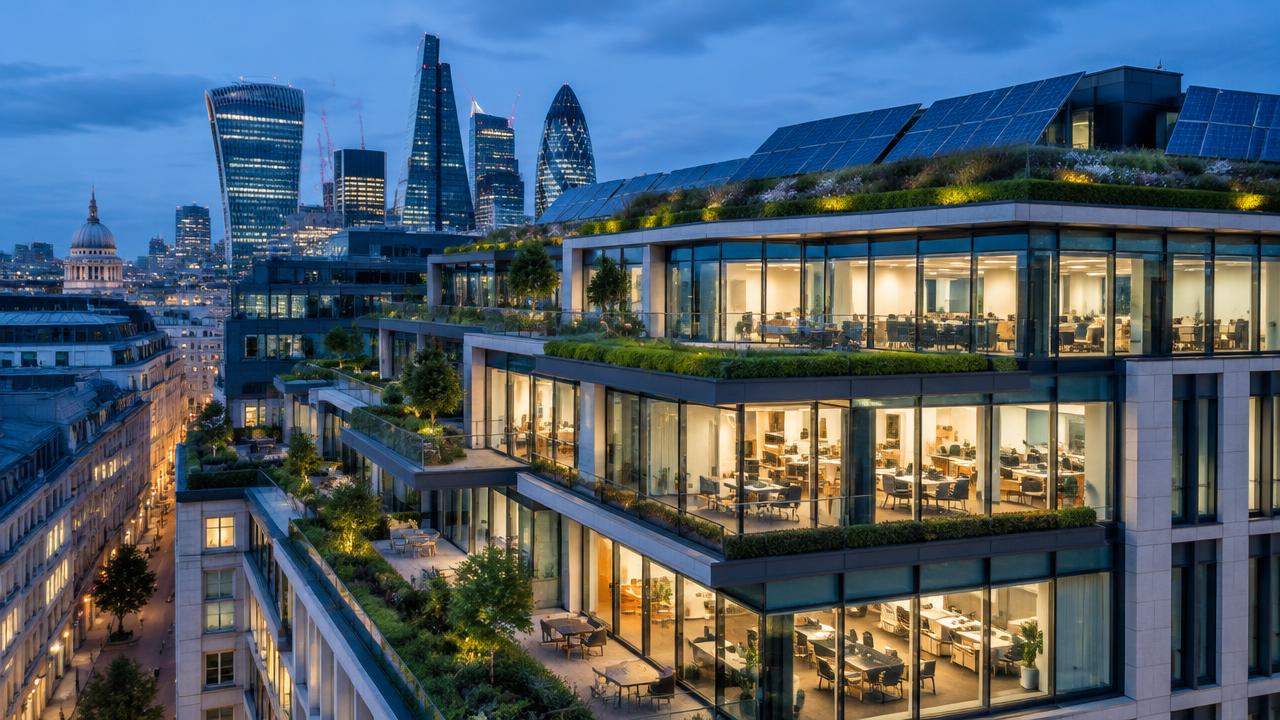 Green loan: City office retrofitBig ticket · £45m illustrative asset valueTokenised SPV share register
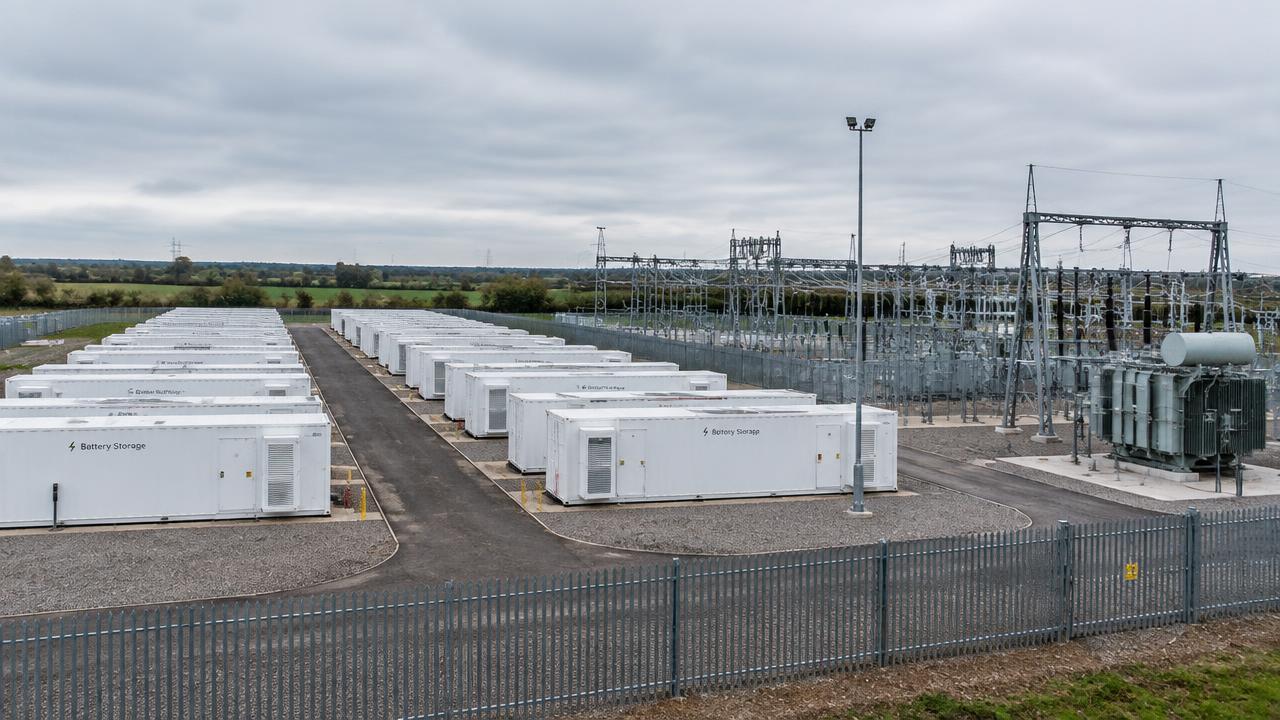 DLT bond: fictional community energy projectLow ticket · £750k illustrative asset valueDemonstration permissioned DLT bond register
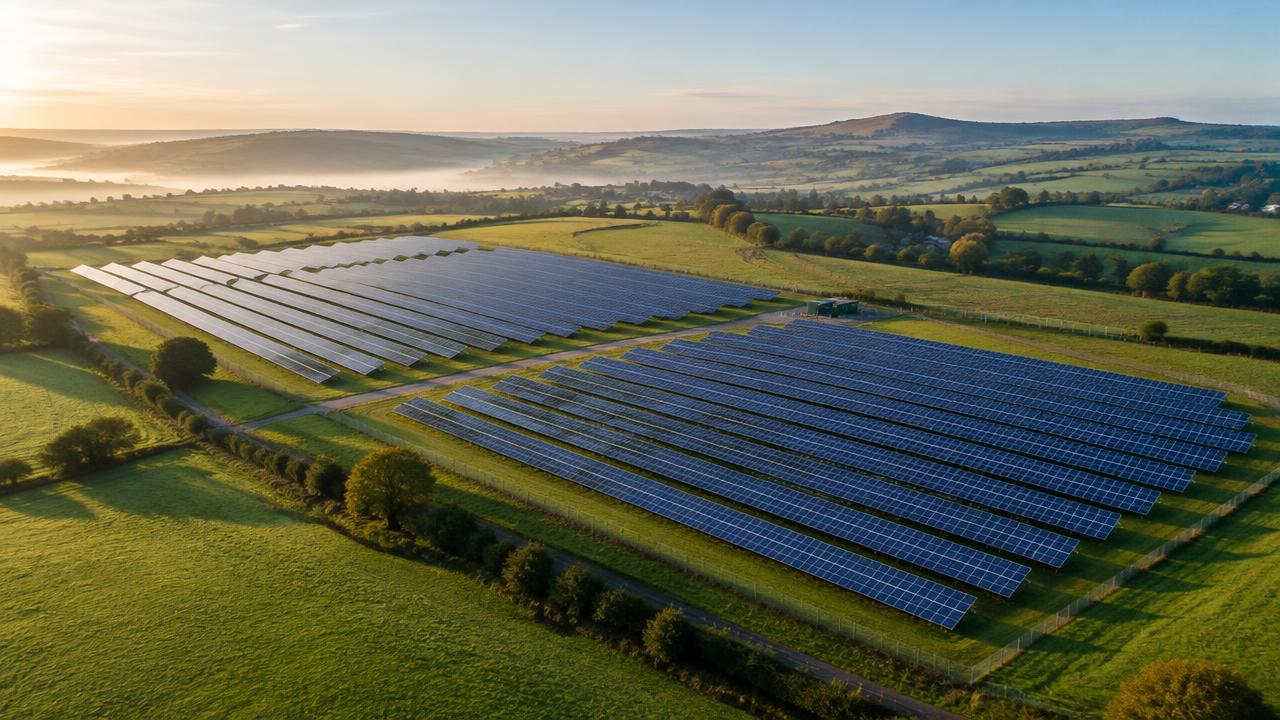 DLT bond: fictional energy pilotEntry-level scale · £75k illustrative asset valueDemonstration permissioned DLT bond register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.