Markets
Tokenised money market funds and the collateral question
A digital fund interest may travel more easily, but its usefulness as collateral depends on legal control, liquidity and the receiver's willingness to accept it.
Monday, 14 September 2026 · 09:00 UTC (demo) · 4 min read · 963 words
 Democratize
A fund interest is not cash
Tokenised money market funds sit at the intersection of two ambitions: making investment records easier to move and making financial resources easier to deploy. The combination invites a tempting shorthand. If an interest in a cash-management fund can move digitally, perhaps it can behave like cash throughout a transaction. That conclusion moves too quickly. A fund interest is a claim governed by fund documents, with an underlying portfolio and an operational process for subscription and redemption.
The distinction matters even when the portfolio contains relatively short-dated instruments. Investors remain exposed to the fund's structure, assets, liquidity arrangements and service providers. A digital wrapper does not convert an investment into a bank deposit or central bank money. Nor should a tokenised fund interest automatically be treated as equivalent to a stablecoin. Each instrument requires its own analysis of the holder's rights, the source of value and the route back to spendable money.
Collateral introduces another layer. An asset can be valuable without being acceptable to a particular counterparty as security. Acceptance depends on the receiver's policies, legal arrangements and ability to realise value if the provider defaults. Tokenisation may make some of these processes more efficient, but it does not settle the commercial decision. The collateral question begins with who will accept the interest, for which obligation and on what terms.
Moving the record is only one step
In conventional collateral processes, institutions establish eligibility, valuation methods, control arrangements and procedures for substitution or enforcement. These requirements do not disappear when an interest is represented on a ledger. A transfer between addresses might be technically simple while leaving uncertainty about whether a valid security interest has been created. Conversely, a legally effective arrangement may require restrictions that limit how freely the token can move.
Control is especially important. A collateral receiver needs confidence that the provider cannot dispose of the same interest inconsistently with the agreement. That may involve a transfer of title, a security arrangement or another legally recognised mechanism, depending on the structure and jurisdiction. Platform permissions can support those mechanisms, but should not be mistaken for the whole legal analysis. The documentation must connect technical actions to enforceable rights.
Eligibility restrictions can also shape the process. Fund interests may be available only to investors meeting specified requirements. If enforcement would transfer an interest to a party that cannot hold it, the receiver needs an effective alternative route to value. A neat digital workflow is insufficient if it breaks precisely when a default occurs. The operating design must account for both ordinary transfers and the less convenient circumstances of enforcement.
Collateral is useful because someone can rely on it under stress, not merely because it can move quickly.
Liquidity has several clocks
A ledger can operate continuously while the fund's dealing, valuation and banking processes follow different schedules. This mismatch is central to claims about always-available collateral. The record may move outside normal business hours, but redemption proceeds may not. The receiver must distinguish the ability to transfer an interest from the ability to obtain cash in the required currency, at the required time and through an accessible payment channel.
Valuation raises a related issue. Collateral arrangements need a method for determining current value and deciding how much protection is required against uncertainty. Haircuts, margin calls and concentration limits reflect the receiver's assessment of risk, not simply the instrument's digital form. If reliable pricing information is unavailable when an obligation falls due, faster transfer does little to solve the resulting shortfall. The relevant system includes market data and governance as well as settlement technology.
Stress makes these distinctions more visible. A receiver may need to redeem or sell an interest while other holders are also seeking liquidity. The fund's terms and applicable rules govern the available responses. It would be wrong to assume uninterrupted convertibility merely because the instrument is described as a cash-management product. Collateral analysis should examine plausible disruption, including service outages and delayed payments, rather than extrapolate solely from routine conditions.
A connected operating model
There is nevertheless a credible operational case to investigate. Better coordination between fund ownership records and collateral systems could reduce manual instructions and provide clearer evidence of an asset's status. A participant might be able to see whether an interest is available, committed or released without reconciling several disconnected messages. The benefit is greater certainty about usable resources, provided every relevant party recognises the record and its legal consequences.
Programmability could support substitutions or releases when agreed conditions are met. Yet automated actions need reliable information about obligations that may exist outside the ledger. They also need procedures for disputed valuations, erroneous instructions and exceptional market conditions. Otherwise, a system designed to reduce operational delay may accelerate an inappropriate transfer. Governance should determine where automation ends and who has authority to intervene without creating uncertainty about the receiver's protection.
Interoperability is consequently more than connecting software. Fund administrators, custodians, collateral receivers and payment providers need compatible definitions and aligned responsibilities. A token accepted within one arrangement may not be usable elsewhere. Moving between networks can introduce additional providers, dependencies and legal questions. Institutions should examine whether apparent portability survives those transitions, including the arrangements for maintaining authoritative records and recovering from an interruption.
For real-asset financing, the connection is indirect but important. More efficient collateral processes could influence how institutions organise liquidity around their wider portfolios. They do not change the duration or saleability of the property and infrastructure exposures underneath those portfolios. The strongest case for tokenised money market funds is therefore specific: improving the mobilisation of an eligible investment within a carefully designed arrangement. That is a meaningful possibility without claiming that fund units have become universal money.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
 Fund units: glasshouse tomatoesBig ticket · £24m illustrative asset valueDigital bond on a regulated DLT venue
 Fund units: water rightsMedium ticket · £9.5m illustrative asset valueERC-3643 on a permissioned EVM chain
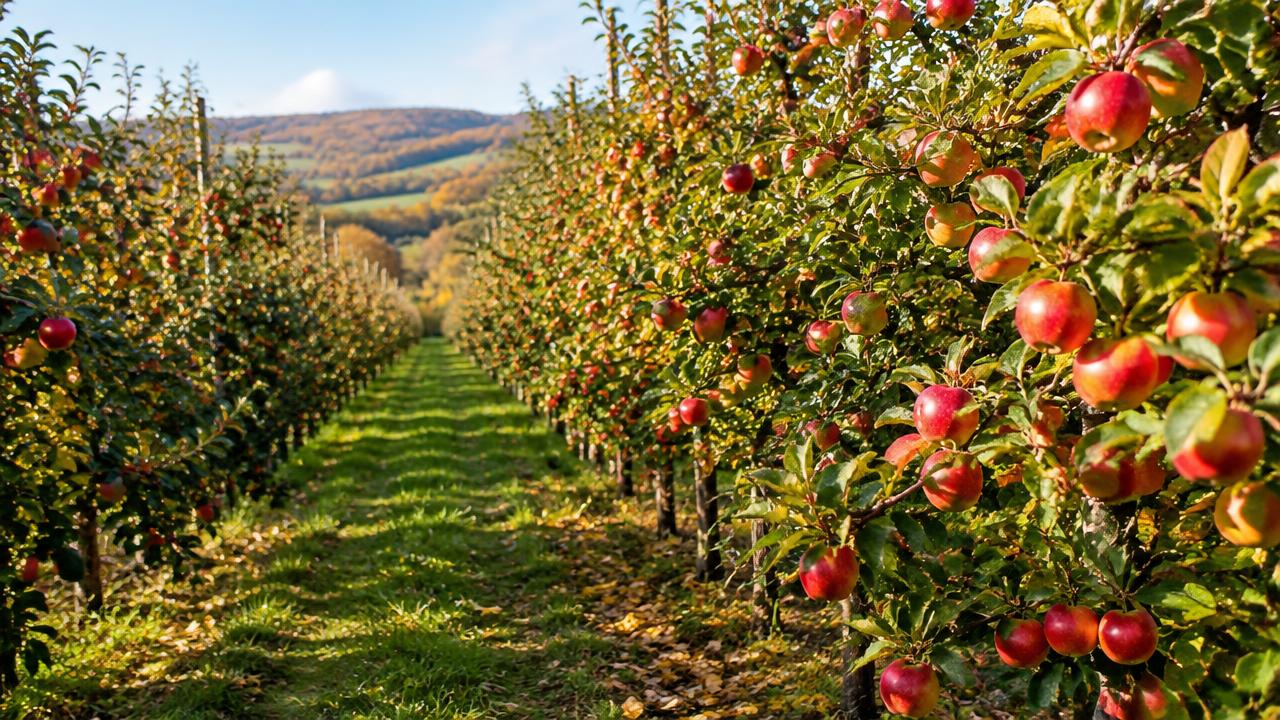 Fund units: apple and pear orchardsBig ticket · £11m illustrative asset valueTokenised SPV share register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.