Regulation
The UK's sandbox approach to digital securities and what it signals
A controlled environment for digital securities points towards institutional experimentation, not a shortcut around the obligations of financial markets.
Thursday, 10 September 2026 · 09:00 UTC (demo) · 4 min read · 954 words
 Democratize
An experiment in market structure
The UK's Digital Securities Sandbox is best understood as a way to examine how market infrastructure might change when securities use distributed ledger technology. Its significance is not that a token receives a general seal of approval. It is that questions about issuance, trading and settlement can be considered within a supervised framework rather than treated solely as abstract technical possibilities. That distinction matters for institutions whose responsibilities extend beyond making a system work in a demonstration.
The FCA and the Bank of England are relevant reference points in this discussion because securities markets involve both conduct and the functioning of financial infrastructure. A digital system can affect investor protection, operational resilience and the management of settlement risk at the same time. The sandbox approach recognises that these concerns interact. A change that improves one stage of a transaction may create dependencies or concentrations elsewhere in the chain.
For readers evaluating a particular proposal, however, broad policy direction is not enough. The applicable rules, scope of permissions and conditions of participation require checking against current official materials. A firm's interest in a sandbox is not admission, and admission is not unrestricted authorisation for every activity. Nor does the existence of a sandbox mean that any proposed instrument, investor group or distribution method falls within it.
Why the boundaries matter
Securities infrastructure has developed around legal categories and institutional roles. Trading venues, settlement systems, registrars, custodians and intermediaries perform distinct functions, even when their processes overlap. Distributed ledgers can challenge the practical division between those functions. A platform might seek to record ownership and coordinate settlement within the same environment. The policy question is not simply whether that integration is possible, but which safeguards must accompany it.
A controlled testing environment can help expose those dependencies. Responsibility for correcting records, managing access and responding to outages needs to be assigned. Participants must know when a transaction becomes binding and how a disagreement is resolved. If a technology provider performs several critical tasks, concentration risk may become more important even as reconciliation becomes easier. Integration can remove handovers without removing the need for independent scrutiny or effective controls.
Boundaries also protect the meaning of the experiment. Limits and conditions can make it possible to learn from activity without assuming that a new arrangement is ready for unrestricted use. That does not make a sandbox outcome trivial. It makes interpretation important. Evidence that a process works under defined conditions should be assessed against those conditions, rather than expanded into a claim that every market can move to the same model.
A sandbox is a framework for answering difficult questions, not a regulatory endorsement of every answer.
Legal certainty is infrastructure
Discussions of digital securities often separate law from technology, as though legal analysis were a final approval stage after engineering is complete. In practice, the legal meaning of the record shapes the engineering. If an entry establishes ownership, access and correction mechanisms carry particular significance. If it merely mirrors another register, reconciliation remains necessary. The system's architecture should express the intended rights rather than leave participants to infer them from an interface.
Settlement provides another example. Participants need certainty about the securities leg, the payment leg and the consequences of a failure between them. A shared ledger may coordinate instructions, but the legal and operational character of the settlement asset still matters. Claims about immediate settlement should therefore be examined alongside arrangements for liquidity, errors and default. Speed is a useful property only when participants understand what has become final and what remains contingent.
The same discipline applies to custody and control. Holding a cryptographic key may be operationally important without answering every question about beneficial ownership or insolvency treatment. Institutions need procedures for lost credentials, unauthorised instructions and provider failure. They also need records that can support disputes outside the platform. A credible regulatory experiment should make these issues more visible, not allow technical terminology to obscure them.
What the signal does and does not mean
The broader signal is a willingness to explore changes to the machinery of securities markets. That is different from a judgement that every asset benefits from tokenisation. Some processes may improve through shared records; others may be served adequately by existing arrangements. The burden remains on a proposed model to explain the problem it solves, the risks it introduces and the reasons its benefits justify the transition costs.
International comparisons require care. The EU DLT Pilot Regime and MiCA are useful reference points in discussions of digital finance, but they should not be collapsed into a single rulebook or treated as interchangeable with UK arrangements. Classification, activity and jurisdiction matter. A digital representation does not erase the distinction between a security and other forms of cryptoasset, nor does it remove the need to examine cross-border distribution and local requirements.
For professional investors, family offices and GCC capital considering UK-linked structures, the practical implication is a more disciplined diligence agenda. Ask which entity performs each role, under what permissions and with which dependencies. Ask whether the proposed activity is a test, a permitted service or an aspiration. Ask what happens when the experiment ends or a provider withdraws. The route out of a controlled environment matters alongside the route into it.
Democratize is a pre-launch UK arranger, not presented here as a sandbox participant or an authorised operator. From that position, the useful editorial lesson is restraint: institutional credibility comes from describing a structure accurately and distinguishing policy ambition from present capability. The sandbox conversation is encouraging where it deepens that discipline. Its value lies in making innovation answerable to the responsibilities that already make securities markets consequential.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
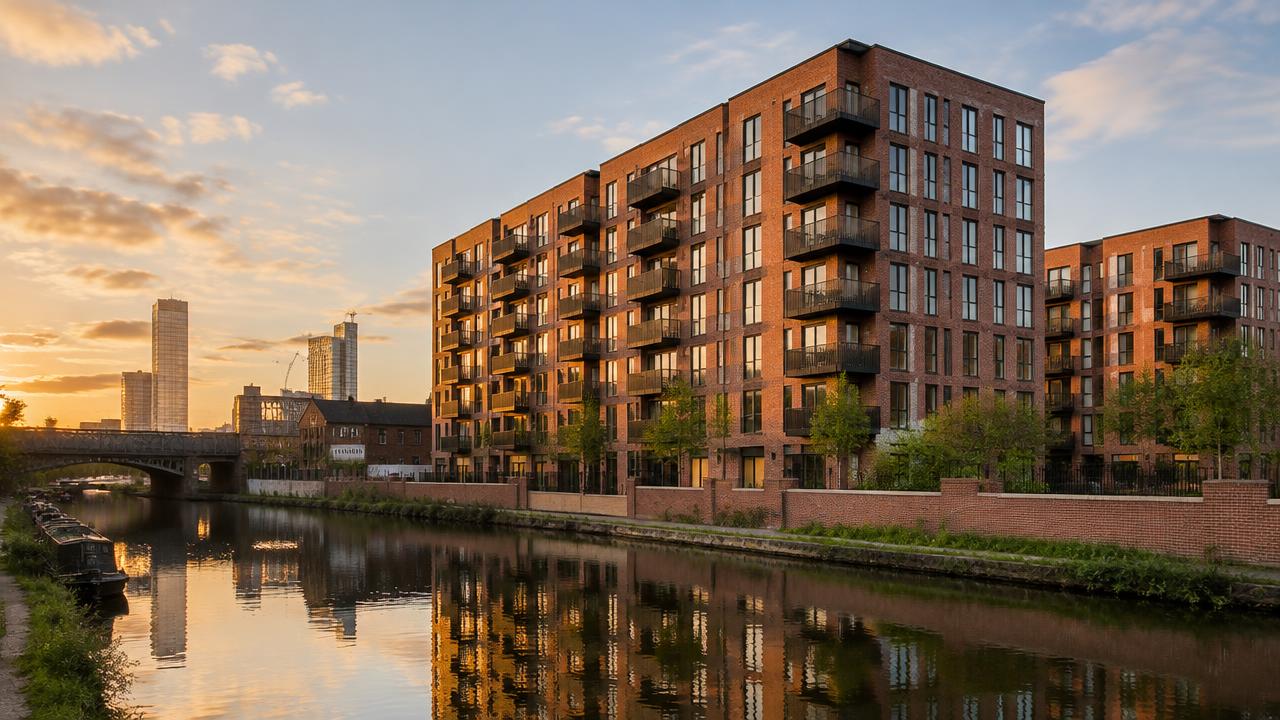 Mezzanine note: Manchester build-to-rentBig ticket · £22m illustrative asset valueDigital bond on a regulated DLT venue
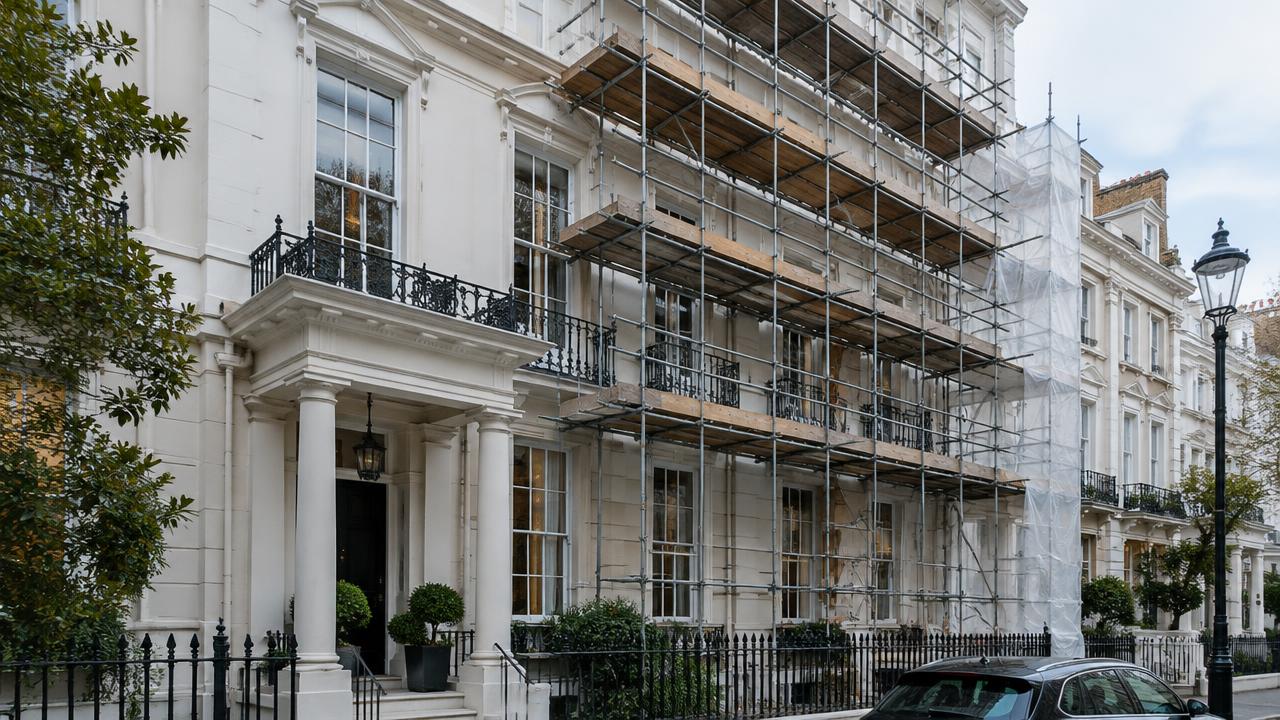 Bridging loan: Mayfair townhouse refurbishmentMedium ticket · £9.0m illustrative asset valueERC-3643 on a permissioned EVM chain
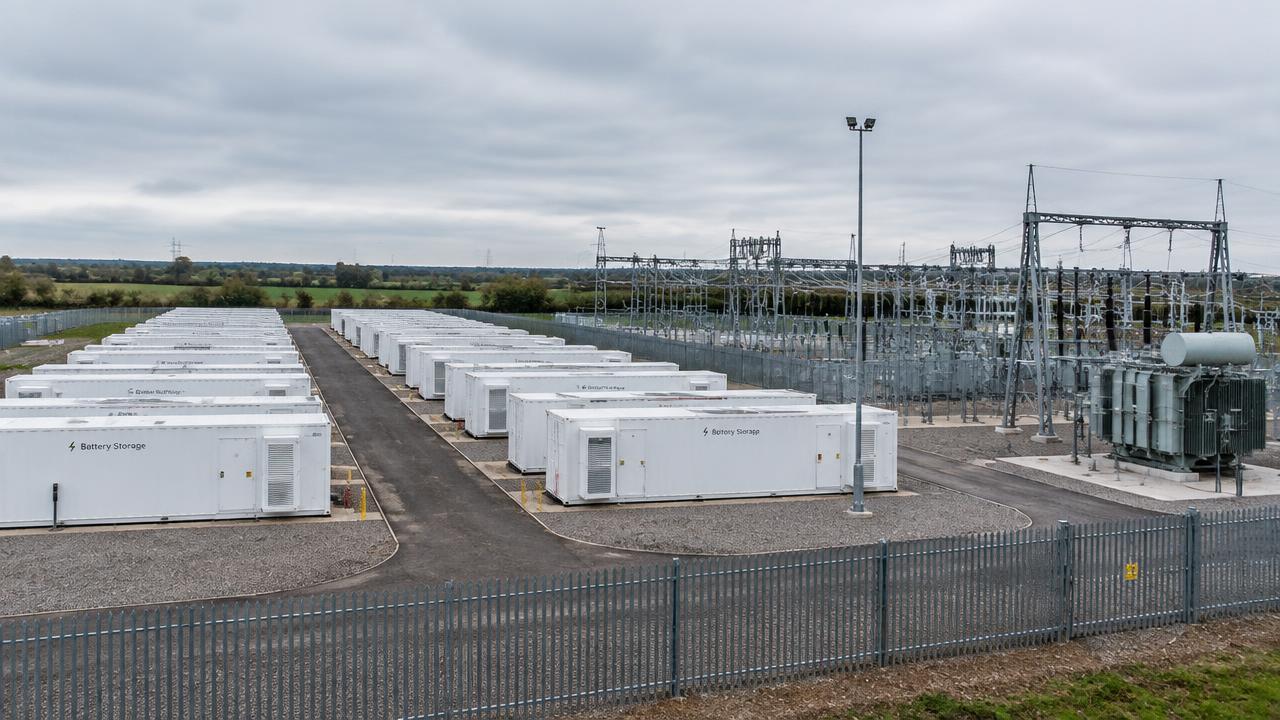 DLT bond: fictional community energy projectLow ticket · £750k illustrative asset valueDemonstration permissioned DLT bond register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.