Outlook
Where tokenisation goes next — a 2027 outlook
The useful question for the year ahead is not how much can be tokenised, but which arrangements can earn lasting confidence through better rights, records and administration.
Monday, 26 October 2026 · 09:00 UTC (demo) · 4 min read · 1,014 words
 Democratize
An outlook built around conditions
An outlook for tokenisation can easily become a catalogue of promised breakthroughs. More assets, faster settlement and wider access sound persuasive until the practical conditions are examined. For the year ahead, a more useful approach is to ask what would have to become true for digital representations of financial interests to deserve a larger role in institutional portfolios. This is a conditional outlook, not a prediction of adoption or returns. Progress should be judged by the quality of arrangements that survive scrutiny, rather than the range of assets that appear in demonstrations.
The central distinction is between representing an interest and improving the way it functions. Almost any contractual claim can be described digitally. Far fewer proposals explain why a shared record improves administration enough to justify its additional dependencies. A credible case might involve clearer ownership records, more reliable reconciliation or better coordination between parties. Those benefits need to be assessed against legal complexity, service costs and operational risk. The relevant comparison is not with an imaginary paper system, but with the existing alternatives available to the particular investor and issuer.
Infrastructure before spectacle
One plausible direction is greater emphasis on the less visible parts of market infrastructure. Identity checks, investor eligibility, corporate actions and reconciliations are not glamorous subjects, but they determine whether an instrument can be administered consistently. Institutions need workflows that fit their governance rather than require exceptional treatment at every step. If tokenisation helps reduce repeated manual interpretation without weakening controls, its usefulness becomes easier to evaluate. That does not require every participant to adopt the same system, but it does require clear boundaries and dependable exchanges of information.
Interoperability is likely to remain a demanding design question rather than a simple feature. Moving a record between systems can affect permissions, legal recognition and access to supporting information. A bridge between networks introduces dependencies of its own. The meaningful test is whether rights remain intelligible and controllable across the whole process, including when a transfer fails. Standards can help organise those relationships, but technical compatibility alone cannot reconcile conflicting legal documents or create agreement about who bears a loss. Those decisions still require explicit contractual and operational arrangements.
Settlement also deserves careful framing. Shorter settlement processes may reduce some exposures while shifting demands onto cash management, funding and error handling. Atomic exchange is a useful concept, but practical arrangements must address the nature of the payment instrument and the consequences of disruption. Institutions will ask whether a proposed improvement applies to the complete transaction or only one part of it. A faster movement of tokens is not necessarily faster completion if approvals, cash conversion or updates to the legally authoritative register still occur elsewhere.
Asset selection becomes more exacting
Another plausible development is sharper differentiation between assets suited to repeatable administration and assets whose economics resist standardisation. A stable contractual payment stream may be easier to describe than a project requiring continuous discretion and fresh capital. Even apparently straightforward assets can contain unusual consent rights or servicing requirements. The lesson is not that complex assets cannot be tokenised, but that complexity must remain visible. A common interface should not flatten important differences between a secured loan, an equity interest and a participation in uncertain future revenue.
The next useful phase of tokenisation would make the investment easier to understand, not merely easier to display.
Real estate and infrastructure illustrate the distinction. Their tangible character can support an intuitive story, yet ownership costs, operating obligations and enforcement remain highly specific. A property does not become divisible in every legal or practical sense because interests in a vehicle are represented by tokens. Infrastructure income can depend on contracts and public decisions that a ledger cannot control. Better administration may still be valuable, but the claim should be proportionate: a clearer record around an asset, not a transformation of the asset's underlying risk.
Private credit raises a related question about information. More frequent reporting can help only if the inputs are reliable and the definitions consistent. Borrower discretion, covenant interpretation and valuation judgement do not disappear when data arrives more quickly. The year ahead could reward proposals that explain these limitations candidly, although there is no certainty that market incentives will do so. Investors can distinguish useful digitisation from cosmetic novelty by asking which decisions improve, which costs change and who remains accountable when the reported picture proves incomplete.
Trust is an operating discipline
Regulation will remain part of that assessment, but a single global settlement should not be assumed. The FCA, European frameworks and other authorities approach different instruments and activities through their respective legal systems. A project may need several analyses rather than one regulatory label. Clearer policy can reduce some uncertainty without removing the responsibility to examine a particular structure. For cross-border investors, including GCC institutions, the practical challenge is to connect local requirements, internal mandates and the actual rights offered, rather than treat digital distribution as jurisdiction-free access.
Commercial durability matters just as much. Service providers need viable arrangements for maintaining records, supporting investors and handling exceptions after the initial issuance. If ongoing administration is underfunded, a sophisticated launch can leave behind fragile infrastructure. Investors should ask how providers can be replaced and how information remains accessible if a platform closes. These are not arguments against innovation. They are conditions for trusting an arrangement whose useful life may outlast the commercial enthusiasm, personnel and technology choices present when it was first designed.
For Democratize, a pre-launch UK arranger connecting real assets with institutional capital as its intended focus, the appropriate outlook is therefore disciplined rather than expansive. The opportunity is to help frame proposals around evidence, enforceability and an understandable operating model, without implying an existing service or completed transaction. The test for the year ahead is whether tokenisation can become less exceptional in the right ways: easier to review, easier to govern and more candid about its limits. Lasting relevance would come from serving investment discipline, not asking investment discipline to accommodate the technology.
Information, not advice.
Marketplace connections
Related tokenisation themes, not recommendations. These fictional Blueprint assets are separate from the reported news; no publisher or source endorses them.
 Mezzanine note: Manchester build-to-rentBig ticket · £22m illustrative asset valueDigital bond on a regulated DLT venue
 Bridging loan: Mayfair townhouse refurbishmentMedium ticket · £9.0m illustrative asset valueERC-3643 on a permissioned EVM chain
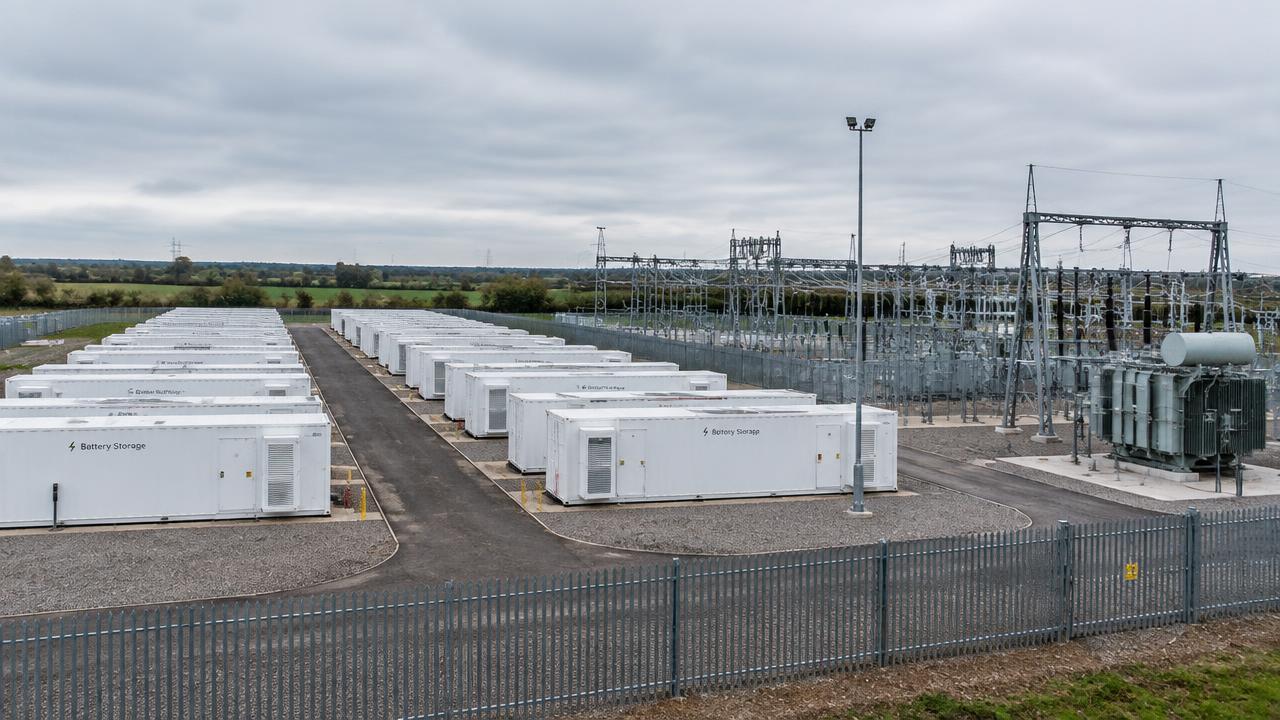 DLT bond: fictional community energy projectLow ticket · £750k illustrative asset valueDemonstration permissioned DLT bond register
Scale bands use whole fictional asset values: entry-level below £100k; low £100k–under £1m; medium £1m–under £10m; big £10m+. Not investment minimums or a statement of suitability. Blueprint: fictional data, not an offer, not live. Information, not advice.
Enjoyed this?
Get new Token+ Intel essays and the weekly tokenisation briefing every Monday.
Subscribe to the briefing
Token+ Intel desk
Claudia Harken
Head of Marketing and Communications
Claudia Harken leads marketing and communications at Democratize.